How do you keep a promised customer advance visible?
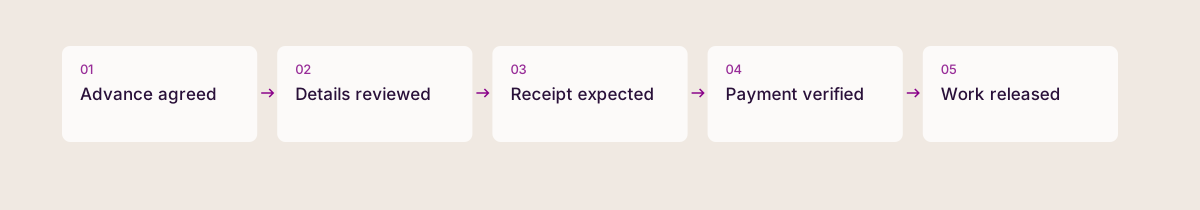
Keep a promised advance visible by linking the expected amount and date to its order and responsible person. Separate the customer’s promise from a confirmed receipt and agree how payment affects purchasing or production. Check outstanding advances regularly, record changed agreements and make any exception clear to the people continuing the work.
Keep these in mind
- An advance promised is different from an advance verified.
- Link the amount to the right customer and order.
- Make production and delivery conditions explicit before work proceeds.
Capture the whole promise
A message saying I will send fifty tomorrow leaves several questions. Which currency? Which order?
Is fifty the deposit, the balance or shorthand for fifty thousand? Does production depend on receipt? A person familiar with the conversation may know, while a colleague does not.
Record the relevant wording and clarify important uncertainty. Save the date in an unambiguous form rather than retaining only tomorrow. If the customer changes the promise, preserve the change and its source.
ICAEW’s cash-flow guidance supports coordinated collection and prompt invoicing. The process here applies that discipline to an agreed advance, before it becomes an overdue mystery.
An illustrative ₹50,000 advance
Imagine a workshop accepts a custom order priced at ₹150,000. The customer agrees to pay a ₹50,000 advance on Tuesday before material purchasing. The owner records the message but does not mark the advance as received.
Purchasing sees that the release condition remains open.
On Tuesday, the finance owner checks the receiving bank record. If payment is absent, the customer-contact owner asks for an update and the team reviews the purchasing date. The order’s remaining balance is determined using verified receipts and approved adjustments, not the promise alone.
| Field | Recorded value |
|---|---|
| Customer and order | Rahul, custom order 104 |
| Agreed advance | ₹50,000 |
| Expected date | Tuesday, stated calendar date |
| Condition | Purchasing begins after receipt is verified |
| State | Expected, not verified |
| Next action | Finance checks receipt; sales follows up if absent |
Keep supporting evidence with the record
Save the accepted quote, the advance agreement and subsequent changes where authorized colleagues can find them. Avoid copying an entire personal conversation when only a small business extract is needed.
The IRS recordkeeping guidance explains the role of supporting documents in business records. Its tax rules are US-specific; the general operational lesson here is to retain evidence supporting a transaction. Follow your own jurisdiction’s accounting and retention requirements.
A bank screenshot from the customer can help identify a reported transfer. It is not a substitute for checking whether the business received the money in the correct account.
Agree a simple release rule
The person buying materials should know whether an advance is required, who verifies it and who may approve an exception. Keep this rule visible before an urgent order reaches the shop floor.
- Confirm the amount, currency, order and expected calendar date.
- Record any condition connecting payment to purchasing or production.
- Assign a payment-verification owner and a follow-up owner.
- Keep reported transfers separate until receipt is checked.
- Record approved exceptions and revised dates with the order.
Use a review queue instead of memory
At the start of each working day, inspect advances expected today and those past their agreed dates. Classify each as awaiting customer action, awaiting verification, disputed or resolved. A list of amounts without next actions merely moves the memory problem onto a screen.
Keep the original advance promise with its order, expected date and responsible person. Check the receiving account through the normal finance process before treating the money as available. If the customer changes the date, record the new agreement and review its effect on purchasing or production.
A clear record helps the next colleague continue the conversation without guessing.
Everyone handling the order should see what was promised, what was checked and what happens next.
Common questions
What should a customer advance record contain?
Link the order, expected amount, promised date and relevant contact. Distinguish the promise from a confirmed receipt and name who checks payment and follows up when the date passes.
What if work starts before an advance arrives?
Record who agreed to the exception, its exposure and later decisions depending on payment. Inform purchasing and production so urgency or silence is not mistaken for authorization to proceed.
Sources & further reading
Primary references for the facts and frameworks discussed. Worked examples and recommendations are Daltn’s own analysis.
- Working together to improve cash flow, ICAEW ↗
Supports coordinated collection and cash-flow practices.
- Recordkeeping, Internal Revenue Service ↗
Supports retaining transaction evidence; US tax context is distinguished.
Published by the team building Daltn. Comparisons are first-party analysis, not independent reviews. Our editorial approach.