How do you match customer payments to the right orders?
Match payments to orders using the transaction reference, amount, receiving account entry and a clear allocation. Treat screenshots as supporting information and check whether repeated images describe the same transfer before recording another receipt. Keep unidentified credits visible with an owner and next check until the appropriate records explain where they belong.
Keep these in mind
- Verify the credit through the receiving bank or payment provider.
- Match identity and reference, not only the amount.
- Keep unresolved receipts visible without guessing an allocation.
Separate four events
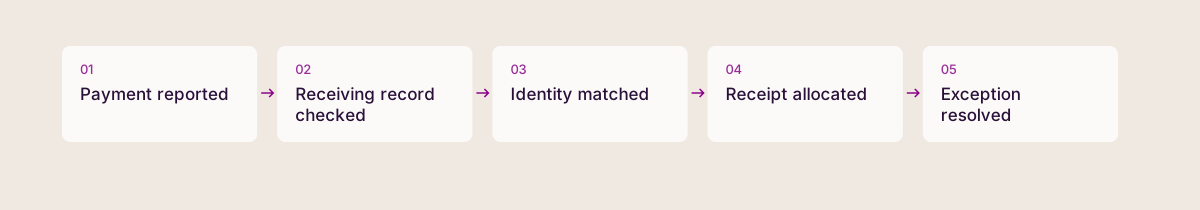
A customer can promise payment, report sending it, have the transfer processed and have the business allocate it. Those events are related but different. When all four become a single paid label, uncertainty disappears from the screen while remaining in the accounts.
NPCI’s UPI FAQ describes transaction history and status checks through participating apps and banks. Use the official receiving-side record and the relevant support route when status is unclear. Do not rely on a forwarded image alone.
This article describes a record-matching procedure, not an automated bank-reconciliation feature or a promise about transaction resolution times.
Collect a small set of matching details
Ask for the amount, date, payer name and transaction reference when needed. Link the reported payment to the expected invoice or order. Avoid collecting PINs, passwords or unnecessary full account details.
When one transfer covers several invoices, ask the customer to specify its allocation. Otherwise, use the agreed accounting policy. Record that allocation.
If a credit arrives without enough information, keep it unidentified until someone checks it.
The IRS recordkeeping guidance describes supporting transaction documents. This is a general recordkeeping principle here; its tax-specific requirements are not presented as Indian rules.
An illustrative matching exception
Two customers each owe ₹20,000. One sends a screenshot for ₹20,000, but the visible payer name differs from the trading name. At the same time, the bank shows a ₹40,000 credit from another customer covering two orders.
Matching by amount alone will not resolve either case.
| Reported or received item | What to verify | Record state |
|---|---|---|
| ₹20,000 screenshot | Receiving credit and payer-to-customer link | Reported, awaiting verification. |
| ₹40,000 bank credit | Customer identity and two-invoice allocation | Verified receipt, allocation pending. |
| ₹10,000 against ₹25,000 invoice | Correct credit and partial allocation | Part paid, ₹15,000 still open. |
| Repeated screenshot | Whether it refers to the same transaction | Duplicate evidence, not another payment. |
Create a daily exception routine
A routine does not have to mean constant checking. Choose a time that fits volume and risk, with more frequent checks when release of goods depends on receipt. Have an authorized reviewer resolve differences rather than asking every salesperson to interpret bank entries.
- Capture the reported transfer with its intended customer and invoice.
- Check the receiving bank or provider record through an authorized person.
- Use references and context to identify the correct transaction.
- Allocate partial or combined payments according to the agreed rule.
- Keep uncertain matches in an exception queue with an owner.
- Record the reviewer and evidence when an item is resolved.
Reduce the work at the source
Give customers clear payment references and ask staff to preserve them. Keep the customer’s trading name and relevant payer identity understandable. Review recurring exceptions to see whether invoice instructions or account setup need improvement.
Keep the payment reference, receiving account entry and allocation to orders together. If one transfer covers several invoices, show the allocation explicitly. If the payer uses a different name, record the connection after checking it.
Keep unresolved credits on an exception list with an owner and next check. Investigate before assigning a customer balance.
The goal is not to remove every review. Give the reviewer enough information to resolve normal cases efficiently. Keep uncertainty visible in unusual cases.
Common questions
How do we avoid counting the same payment twice?
Compare the reference, amount, date and receiving account entry. Repeated screenshots can describe one transfer. Preserve supporting documents while recording the receipt and its allocation only once.
What should happen to an unidentified bank credit?
Keep it on an unresolved list with an owner and next check. Investigate authorized records and customer references. Do not guess an allocation merely to make a customer balance look complete.
Sources & further reading
Primary references for the facts and frameworks discussed. Worked examples and recommendations are Daltn’s own analysis.
- UPI Frequently Asked Questions, NPCI ↗
Supports using transaction history, status and official bank or app support.
- Recordkeeping, Internal Revenue Service ↗
Supports transaction evidence; no local tax or reconciliation authority is implied.
Published by the team building Daltn. Comparisons are first-party analysis, not independent reviews. Our editorial approach.