How can business partners keep one clear customer balance?
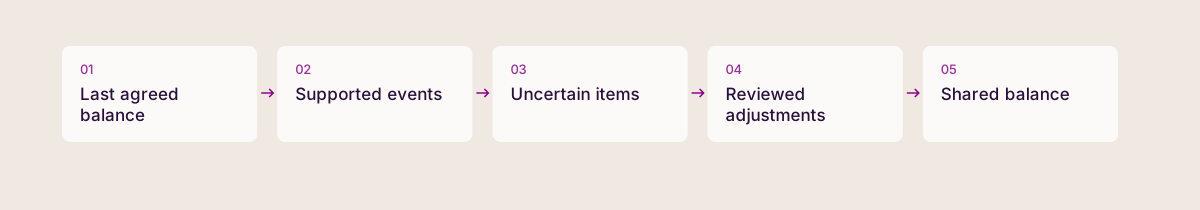
Partners need one understandable customer account history with traceable receipts, discounts, credits and unresolved questions. Reconcile differences from the last agreed balance using supporting records rather than choosing the more confident recollection. Agree who may authorize adjustments and make each decision visible so the same change is not applied twice.
Keep these in mind
- A balance needs a traceable event history, not only a current total.
- Credit promises, discounts and received payments are different events.
- Disagreement should produce a reconciliation task rather than an overwritten number.
Agree what each number means
One partner may quote the total order value while another subtracts an advance that was only promised. A salesperson may have approved a discount that accounts has not seen. The disagreement can arise from different definitions rather than dishonesty or arithmetic.
Choose the authoritative accounting record and define who can change it. Keep operational expectations beside it without mixing them into verified figures. If a customer asks for a balance during a dispute, say what has been confirmed and what remains under review.
The SBA’s business-management guidance emphasizes proper bookkeeping and financial understanding. The practical application is to make the basis of a shared balance explainable to both partners.
Reconstruct an illustrative disagreement
Suppose an order totals ₹80,000. The bank confirms a ₹20,000 receipt. One partner approved a ₹5,000 discount, but the approval was not passed to accounts.
Another partner remembers a customer saying a further ₹10,000 would be sent.
The confirmed balance before applying the approved discount is ₹60,000. If the discount is valid and recorded correctly, it becomes ₹55,000. The promised ₹10,000 remains expected until verified.
Do not reduce the balance to ₹45,000 merely because somebody remembers the promise.
| Event | Effect on confirmed balance | Evidence |
|---|---|---|
| Order accepted | ₹80,000 starting amount | Accepted order. |
| Receipt verified | Less ₹20,000 | Receiving bank record. |
| Discount approved | Less ₹5,000 after correct recording | Authorized decision. |
| Payment promised | No receipt deduction yet | Customer message and expected date. |
| Confirmed remaining amount | ₹55,000 | Subject to the stated approved entries. |
Resolve differences from evidence
Begin from the last balance everyone accepted. List later invoices, receipts, credits, returns and adjustments in date order. Mark uncertain items instead of choosing the lower or higher total to end the conversation.
IRS recordkeeping guidance explains why supporting documents matter for business transactions. Its tax context is US-specific; the operational principle is that entries should have evidence. Use the relevant local accounting rules for treatment and retention.
If two people recorded the same receipt, link the duplicate evidence to one transaction. If a payment covers several orders, document the allocation. The customer should not have to explain the same payment repeatedly because the partners use different lists.
Create a short partner agreement
Agree the update rules before the next disagreement. A shared spreadsheet or accounting system can work if responsibility and evidence are clear. A new tool without those rules can preserve two conflicting totals more efficiently.
- Choose the authoritative account record and the people allowed to update it.
- Define separate states for expected, reported and verified receipts.
- Record discount and credit authority with supporting evidence.
- Reconcile differences from the last agreed point.
- Assign unresolved items an owner and review date.
- Check a sample of account changes together at a regular interval.
Common questions
How should partners resolve different customer balances?
Start from the last agreed balance and compare confirmed receipts, credits, adjustments and invoices. Keep disputed items visible with an owner. Choosing a recollection without evidence postpones the next disagreement.
How can partners prevent conflicting discount decisions?
Agree who may authorize discounts, the limits and where decisions are recorded. Pass the agreement to the account owner. Keep adjustments traceable so each is applied once and understood by both partners.
Sources & further reading
Primary references for the facts and frameworks discussed. Worked examples and recommendations are Daltn’s own analysis.
- Manage your business, US Small Business Administration ↗
Supports bookkeeping and financial-record discipline.
- Recordkeeping, Internal Revenue Service ↗
Supports evidence for transaction entries; US tax context is not generalized.
Published by the team building Daltn. Comparisons are first-party analysis, not independent reviews. Our editorial approach.