How should you evaluate an early-payment discount?
An early-payment discount exchanges part of your margin for an earlier receipt of customer money. Calculate the cost of the timing gained and compare realistic financing or collection alternatives before offering it. Agree eligibility, preserve the discount decision and confirm the payment so a tactic does not become an unexplained pricing policy.
Keep these in mind
- Calculate the cost on the cash received and days accelerated.
- Check whether customers would have paid early without the discount.
- Keep approved discounts, credits and verified payments traceable.
Separate the commercial questions
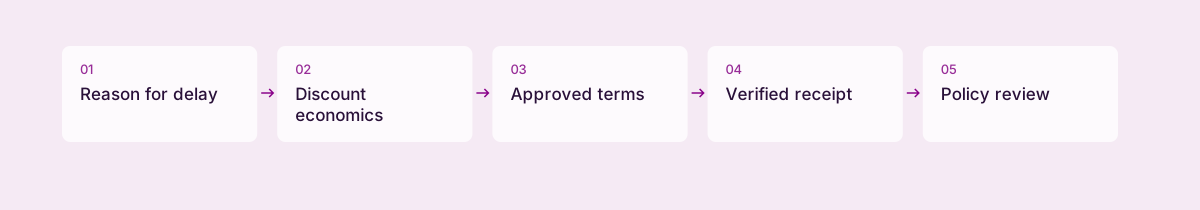
First ask why payment is late. A customer missing a purchase-order reference needs corrected paperwork. A customer disputing quantity needs resolution.
Offering a discount before identifying the cause can give away margin without changing payment timing.
ACCA’s accounts-receivable-management guidance discusses early-settlement discounts as one way to accelerate collection. It also examines their cost. Apply that cost discipline before making an offer.
A fixed early-payment term is agreed in advance. Dynamic discounting varies the offer with timing. Both require an approved amount and a clear rule.
Different ad hoc deals for every invoice become difficult to control.
Work through an illustrative offer
Suppose an invoice is ₹100,000, due in 30 days. The business offers 2% off if paid in ten days. It would receive ₹98,000, giving up ₹2,000 to bring payment forward by 20 days.
A simple annualized comparison is ₹2,000 ÷ ₹98,000 × 365 ÷ 20, approximately 37.2%. This is a comparison rate, not the actual yearly charge on a loan, and it ignores compounding and other details. It shows why a small-looking percentage can be expensive for a short acceleration.
| Item | Amount or timing |
|---|---|
| Full invoice | ₹100,000 |
| Discount | ₹2,000 |
| Cash received early | ₹98,000 |
| Days accelerated | 20 |
| Simple annualized comparison | About 37.2% |
Count behavior that may not change
Some customers already pay within ten days. Giving them the discount reduces proceeds without accelerating cash. Others may take the discount and still pay late unless the terms and approval process are clear.
Include both possibilities in the evaluation.
ACCA’s trade-receivables guidance explains settlement discounts and their accounting treatment in its teaching context. Actual tax and accounting treatment should follow the business’s applicable rules and professional advice.
Compare alternatives such as faster invoicing, deposits, staged billing, better credit checks or an available financing facility. The right choice depends on cost, risk, customer expectations and the contract.
Run a controlled policy test
Choose a limited customer group and define the terms before sending invoices. Do not ask staff to improvise a discount while a customer waits on the phone. Make it clear who can approve exceptions.
- Identify the actual collection delay and whether timing can change.
- Calculate discount cost and expected acceleration.
- Estimate take-up, including customers who would already pay early.
- Agree eligibility, dates, approval and accounting treatment.
- Review verified receipt dates, total discounts and net cash effect after the trial.
Keep the record understandable
A payment record should show the original amount, approved discount or credit, amount received and remaining balance. Preserve the evidence supporting each adjustment. A casual message saying settled should not erase an unexplained difference.
Keep the discount agreement beside the invoice and check the receiving account before closing the payment. Record the amount waived, the amount received and the reason for any difference. Give unusual adjustments to the person responsible for commercial or finance decisions.
This lets the next colleague understand the result without treating a casual message as a completed reconciliation.
If a discount becomes permanent because customers expect it, evaluate the effective selling price and margin. A temporary cash-flow tactic can quietly become a pricing policy unless someone reviews the result.
Common questions
How should we evaluate an early-payment discount?
Calculate the margin given up for the time gained and compare realistic financing or collection alternatives. Consider eligibility and whether the offer changes payment behavior before making it a standing policy.
What must the payment record show after a discount?
Preserve the original amount, agreed discount or credit, amount received and remaining balance. Check the receiving account and explain differences so another colleague can understand how the invoice was closed.
Sources & further reading
Primary references for the facts and frameworks discussed. Worked examples and recommendations are Daltn’s own analysis.
- Accounts receivable management, ACCA ↗
Supports evaluating early-settlement discounts and their cost.
- Trade receivables and revenue, ACCA ↗
Explains settlement discounts and receivable adjustments in an accounting teaching context.
Published by the team building Daltn. Comparisons are first-party analysis, not independent reviews. Our editorial approach.