Why does business AI need databases and review?
Business AI needs accepted records, clear calculations and source evidence alongside language understanding to produce dependable answers. A database can calculate correctly from a mistaken payment, duplicate entry or wrong customer match. Define each event, review consequential changes and preserve corrections so people can understand the balance and resolve disagreements.
Keep these in mind
- Valid structure does not establish a true business event.
- Use exact amounts and defined calculations for money.
- Preserve corrections and distinguish expected from confirmed events.
Two different kinds of correctness
Imagine an invoice for ₹12,000 and an advance of ₹4,000. Subtraction gives ₹8,000. The calculation can be correct while the record is wrong.
The advance might belong to another invoice or represent a promise. The system needs both arithmetic correctness and evidence that the inputs belong together.
Language interpretation and record maintenance have different strengths. A model can propose meaning from messy text. A database can require identifiers and relationships.
A rule can calculate a remaining amount from accepted events. None of these components can recover a fact that was never captured or confirmed.
Constraints reject some bad records
A constraint is a rule the database checks when saving data. PostgreSQL documents unique, foreign-key and check constraints. They can prevent a duplicate identifier, a broken relationship or a value outside a permitted range.
For an order system, require a real customer identifier and a currency. Make an imported source event unique so a retry does not create the same payment twice.
These rules reduce known failure modes. They cannot prove that the customer really paid or that the uploaded document is genuine.
Keep event meanings separate
This illustrative record design avoids turning a conversational intention into a settled transaction.
| Source statement | Accepted event | Effect on operational context |
|---|---|---|
| “I will pay tomorrow” | Payment expected | Follow-up or expected-date record |
| Customer sends screenshot | Payment evidence received | Await authorized confirmation |
| Bank or accounting confirmation checked | Payment confirmed | Apply according to the accounting workflow |
| “Ignore the earlier amount” | Correction requested | Review the prior event and reason |
Use appropriate arithmetic and transaction handling
Amounts should use a defined currency and precision. PostgreSQL’s numeric-type documentation distinguishes exact decimal types from inexact floating-point types. This matters when software computes totals instead of asking a model to invent the answer in prose.
Concurrent updates also need engineering. Two staff members may change the same order at once. The transaction-isolation documentation explains how concurrent database activity is controlled.
A reliable application must handle conflicts and retries visibly. Calling a system deterministic does not remove those implementation responsibilities.
Design a correction that people can understand
Suppose a reviewer discovers that the advance belongs to invoice I-42 instead of I-41. Retain the original event and record the correction.
Do not silently rewrite history so nobody can explain yesterday’s balance. The display can show the current accepted value while preserving the sequence that produced it.
Use a change summary: previous customer or invoice, new customer or invoice, reason, source and reviewer. This helps a colleague answer later questions using the recorded evidence. They can understand the decision without finding its original owner.
Run a record-integrity exercise
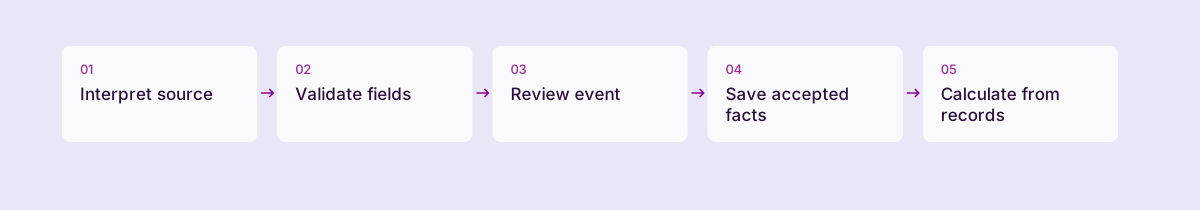
Choose a fictional customer with two invoices and one partial payment. Feed the workflow the same note twice, a revised invoice and a screenshot with no matching transaction. The accepted outcome should remain understandable after every step.
- Define which events affect the operational amount due.
- Check identity, currency and source before accepting a change.
- Reject or flag duplicate source events.
- Calculate from accepted records using defined rules.
- Reconcile with the authoritative accounting or bank records.
Common questions
Why can a correctly calculated balance still be wrong?
The arithmetic may use an incomplete or incorrectly matched event. A promised advance is different from a confirmed receipt, and a receipt may belong to another invoice. Check identity, event meaning, duplicates and authoritative financial evidence before relying on the total.
What should happen when a financial record is corrected?
Preserve enough history to explain the earlier value, the accepted correction and its reason. Link the supporting evidence and responsible reviewer. Ensure that the current operational view and the authoritative financial process use the resolved information consistently.
Sources & further reading
Primary references for the facts and frameworks discussed. Worked examples and recommendations are Daltn’s own analysis.
- PostgreSQL constraints ↗
Documents database validation and relationship constraints.
- PostgreSQL numeric types ↗
Explains exact decimal and inexact floating-point representations.
- PostgreSQL transaction isolation ↗
Explains concurrency behavior and transaction conflicts.
Published by the team building Daltn. Comparisons are first-party analysis, not independent reviews. Our editorial approach.