Where does working capital get stuck in a business?
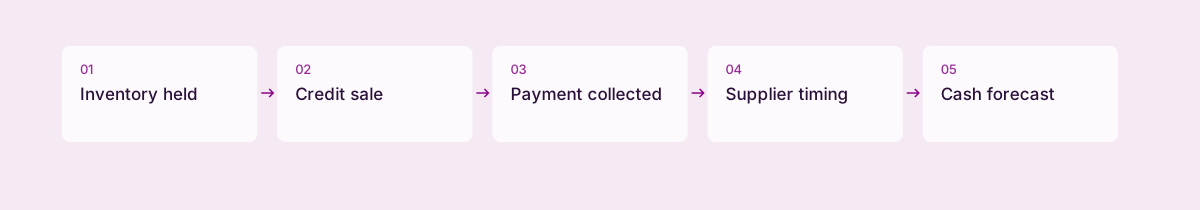
Working capital gets tied up between paying for stock and collecting money from completed sales. Review inventory, collection and payable timing together, using consistent accounting definitions and the underlying transactions. Choose actions that remove unnecessary delays while preserving critical stock, supplier relationships and a distinction between expected and confirmed receipts.
Keep these in mind
- Cash conversion cycle equals inventory days plus receivable days minus payable days.
- Use average balances and matching sales or cost figures.
- Improve the cause of delay without damaging supply or customer relationships.
Understand the three parts
Inventory days estimate how long inventory remains before sale. Receivable days estimate how long credit sales take to collect. Payable days estimate how long the business takes to pay suppliers.
BDC’s cash-conversion-cycle guide explains the operating cash journey.
Calculate inventory days as average inventory ÷ cost of sales × days in the period. Calculate receivable days as average trade receivables ÷ credit sales × days in the period. Calculate payable days as average trade payables ÷ credit purchases × days in the period.
Some analyses use cost of sales as a proxy for purchases; state that choice because it changes interpretation.
Use consistent treatment of taxes, returns and balances. Ask your finance professional to help align the measures with your accounts. A precise-looking ratio built from mismatched figures can mislead.
An illustrative manufacturer’s cycle
Suppose a manufacturer estimates 45 inventory days, 30 receivable days and 25 payable days. The cash conversion cycle is 45 + 30 − 25 = 50 days. This is an illustrative calculation, not an industry target.
Suppose better invoice completeness reduces receivable days to 24, with other components unchanged. The estimated cycle becomes 44 days. That improvement does not directly tell you how much profit increased or whether the month’s cash balance will be positive.
| Component | Baseline | After a collection-process change |
|---|---|---|
| Inventory days | 45 | 45 |
| Receivable days | 30 | 24 |
| Payable days | 25 | 25 |
| Cash conversion cycle | 50 days | 44 days |
Work through your cash cycle
Use consistent figures from your accounting records.
Calculated in your browser. Numbers are not saved or sent.Find the cause inside each average
For inventory, separate slow-moving finished goods from essential components with long supplier lead times. Cutting both equally may cause shortages. For receivables, inspect missing approval documents, disputes and genuine credit risk.
For payables, distinguish negotiated terms from overdue bills.
The RBC working-capital guide presents the CCC relationship as DSO + DIO − DPO. Treat that as a diagnostic relationship, not permission to delay every supplier payment. Damaging a critical supplier can create a much larger operating problem.
Seasonality matters. A business building stock before a busy season can show a longer cycle for a valid reason. Compare similar periods and keep the sales forecast visible.
Turn the measure into a focused action
Choose one component and a specific cause. For example, ensure a buyer’s purchase-order reference is recorded before delivery so invoices do not wait for correction. Assign an owner and measure actual progress.
- Choose a representative period and consistent accounting definitions.
- Calculate average inventory, trade receivables and trade payables.
- Use matching cost, credit-sales and purchase figures.
- Inspect the oldest balances and record why they remain open.
- Change one repeatable cause and compare similar periods.
- Keep a separate weekly forecast of dated cash receipts and payments.
Keep operational evidence separate from settlement
A customer’s promise to pay belongs in expected receipts. It should not reduce the receivable until the relevant payment or adjustment is verified. The same applies to a screenshot suggesting a transfer.
Keep expected receipts, disputed amounts and confirmed transactions clearly separated. Assign an owner to missing documents and overdue checks, and use the accounting records to reconcile the totals. If an expected receipt moves, update the cash plan and identify the decisions affected.
A clear explanation of timing is more useful than a ratio with no underlying action.
A useful working-capital review ends with a few named actions, not only a lower target ratio. Ask what will change in purchasing, delivery paperwork or collections this week.
Common questions
How is the cash conversion cycle calculated?
Add inventory days and collection days, then subtract payable days using consistent periods and definitions. Inspect the actual timing of purchases and receipts before making decisions from the result.
Can a negative cash cycle still involve risk?
Yes. Collecting before paying suppliers helps timing, but deposits, delivery obligations, inventory losses and supplier dependence still matter. Review actual cash commitments rather than treating the ratio’s sign as a verdict.
Sources & further reading
Primary references for the facts and frameworks discussed. Worked examples and recommendations are Daltn’s own analysis.
- Cash conversion cycle: an essential tool to boost your cash flow, BDC ↗
Supports the operating cash-cycle concept.
- Your Guide to Working Capital Management, RBC Royal Bank ↗
Supports the DSO + DIO − DPO relationship.
Published by the team building Daltn. Comparisons are first-party analysis, not independent reviews. Our editorial approach.