What should you check before offering a discount?
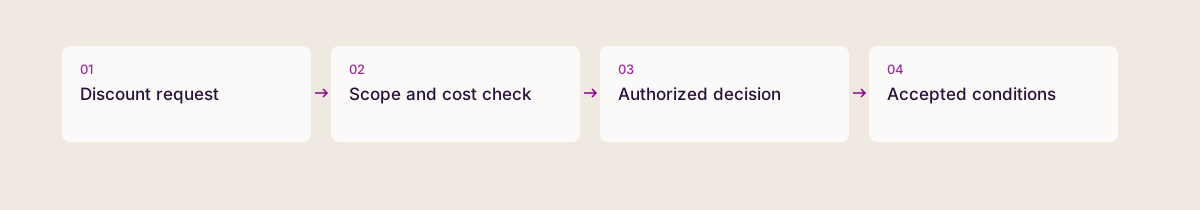
A clear discount process connects the proposed price with scope, cost assumptions, customer history and the conditions behind the request. Compare like with like before using an earlier quote as a reference for a different order or specification. Record the authorized decision and what the customer agrees in return so later changes remain understandable.
Keep these in mind
- Compare the same scope before treating an old quote as a price reference.
- Separate an illustrative margin calculation from the business’s actual full costs.
- Record who approves the concession and which conditions the customer accepts.
Find the reason for the concession
A larger quantity or reduced scope may prompt a discount request. A competing offer may also use a different specification.
Those situations deserve different responses. Ask what changes with the discount instead of treating the requested percentage as the whole decision.
The SBA’s management guidance emphasizes understanding business finances. The procedure here is a record-keeping method for a pricing discussion. It does not set the right price for a particular business or replace an accountant’s assessment of costs and profitability.
Use a calculation the team can inspect
Consider an illustrative job priced at ₹10,000 with ₹7,000 in assumed variable costs. The amount left toward fixed costs and profit is ₹3,000.
If the price falls to ₹9,000 and those assumed costs stay unchanged, that amount becomes ₹2,000. The price fell by ₹1,000, and so did the contribution.
This simplified example excludes other costs, tax treatment and changes in payment or delivery terms. The SBA’s break-even guidance explains the relationship among selling price, variable costs and fixed costs. Use actual verified assumptions for a real decision, and label estimates clearly.
| Item | Original example | Discounted example |
|---|---|---|
| Selling price | ₹10,000 | ₹9,000 |
| Assumed variable costs | ₹7,000 | ₹7,000 |
| Contribution toward fixed costs and profit | ₹3,000 | ₹2,000 |
| Scope or terms changed? | Original assumptions | Must be reviewed separately |
Compare the old job with the new one
An earlier quote can explain a customer’s expectation while being unsuitable for today’s work. Check specification, quantity, delivery, payment terms and any exceptional concession. A copied number without its conditions can become an accidental standing price.
In an illustrative print order, last month’s rush delivery was removed this month but the paper specification increased. Those changes pull costs in different directions.
Record the current scope and the reason for the offered price. Update cost assumptions before using a suggested margin.
Keep approval separate from negotiation
Let the person handling the conversation gather the context and propose terms. Name the person who can approve a concession and the circumstances that require escalation. That supports a calm reply when the request falls outside the agreed authority.
Keep the customer, accepted quote and assumptions together so the person deciding the discount can inspect them. Compare the same specification, quantity and payment terms.
An old price is a reference point rather than an automatic answer. If the conditions changed, record why the new offer differs so the next negotiation starts from a clear explanation.
Save the conditions, not just the final number
When a concession is approved, record what the customer agreed in return: revised scope, quantity, timing or payment terms. If the customer later changes those conditions, the team can recognize that the pricing decision needs review again. This makes the next conversation more specific and reduces reliance on memory.
- Record the requested concession and the customer’s stated reason.
- Compare the proposed work with the scope behind any earlier price.
- Check cost assumptions and payment or delivery conditions with the responsible person.
- Have an authorized reviewer approve the proposed terms.
- Save the accepted amount, conditions and approval source together.
- Revisit the decision if the customer changes those conditions.
Common questions
When can a discount make commercial sense?
A discount can support a specific exchange, such as changed scope, quantity or payment terms. Record the reason and conditions so the team can judge the whole offer rather than the percentage alone.
How should an earlier price inform a new quote?
Use it as a reference, then compare specification, quantity, timing and cost assumptions. If the conditions differ, record the reason for the new amount so the next conversation starts from a clear explanation.
Sources & further reading
Primary references for the facts and frameworks discussed. Worked examples and recommendations are Daltn’s own analysis.
- Manage your business | U.S. Small Business Administration ↗
General bookkeeping, business continuity and marketing guidance; no jurisdiction-specific legal advice derived.
- Plan your business | U.S. Small Business Administration ↗
Break-even analysis and the relation between price, variable costs and fixed costs.
Published by the team building Daltn. Comparisons are first-party analysis, not independent reviews. Our editorial approach.